
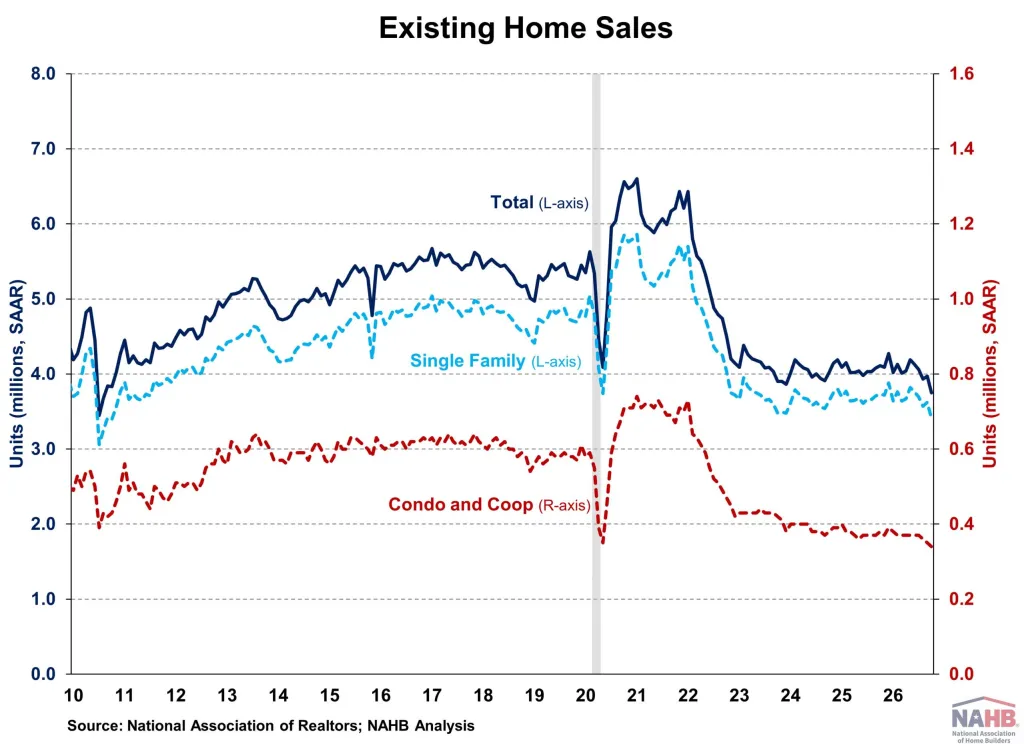
In October, existing home sales experienced a 16-year low following a brief rebound last month.
Since mid-September, mortgage rates have risen above 7%, and home prices remain elevated.
Consequently, purchasers have continued to remain passive.
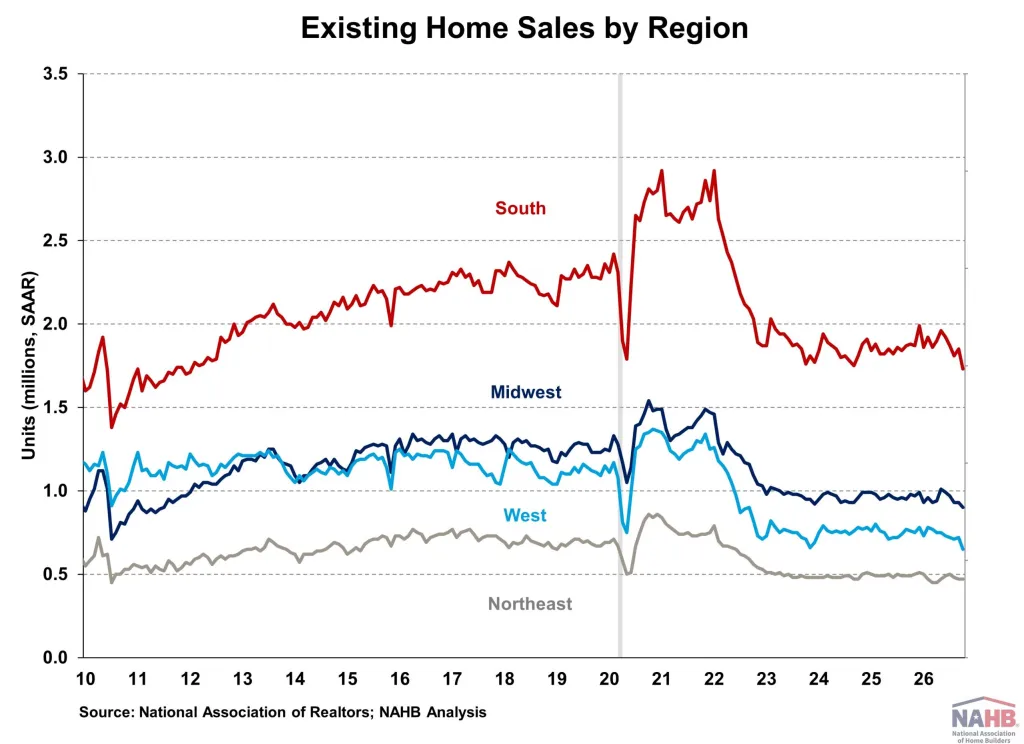
Sales decreased in all four regions, with the West experiencing a record-low, and the Midwest and South experiencing decade-lows.
The for-sale inventory is approaching pre-pandemic levels as a result of the extended period of time that buyers are waiting for rate relief, which has led to a rise in the number of homes on the market.
According to the National Association of Realtors (NAR), the seasonally adjusted annual rate of 3.75 million for total existing home sales, which encompasses single-family homes, townhomes, condominiums, and co-ops, decreased by 5.5% in October.
This was the lowest level since August 2010.
Sales decreased 8.8% from the previous year on a year-over-year basis.
The existing home inventory level increased by 1.3% from September and by 4.6% from a year ago in October, reaching 1.59 million units.
October’s unsold inventory is currently at a 5.1-month supply, which is an increase from 4.7-months in September and 4.4-months a year ago, at the current sales rate.
This was the most abundant month’s supply since November 2015.
A balanced market is generally defined as having an inventory of 4.5 to 6 months’ supply.
In October, the median duration of homes on the market was 35 days, which represents an increase from the previous month’s median of 33 days and the previous year’s median of 34 days.
In October, the percentage of individuals who were purchasing for the first time was 29%.
The share was down from 31% in September and 32% from a year ago.
The all-cash sales share in October was 29% of transactions, which is an increase from 27% last month but remains consistent with October 2025.
Changes in interest rates have a lesser impact on purchasers who pay in cash.
The median sales price of all existing homes in October was $416,700, which represents a 0.4% increase from the previous year.
This month represents the 40th consecutive month of year-over-year growth.
$365,100 was the median condominium/co-op price in October, representing a 0.3% increase from the previous year.
In the majority of markets, the recent increase in home inventory will result in a downward pressure on resale home prices in 2026.
In October, the four major regions experienced a mixed bag of existing home sales.
The Northeast remained unchanged, while sales declined in the West (-9.7%), South (-6.5%), and Midwest (-3.2%).
Sales decreased in all four regions on a year-over-year basis, with the Northeast experiencing a 4.1% decline and the West experiencing a 14.5% decline.
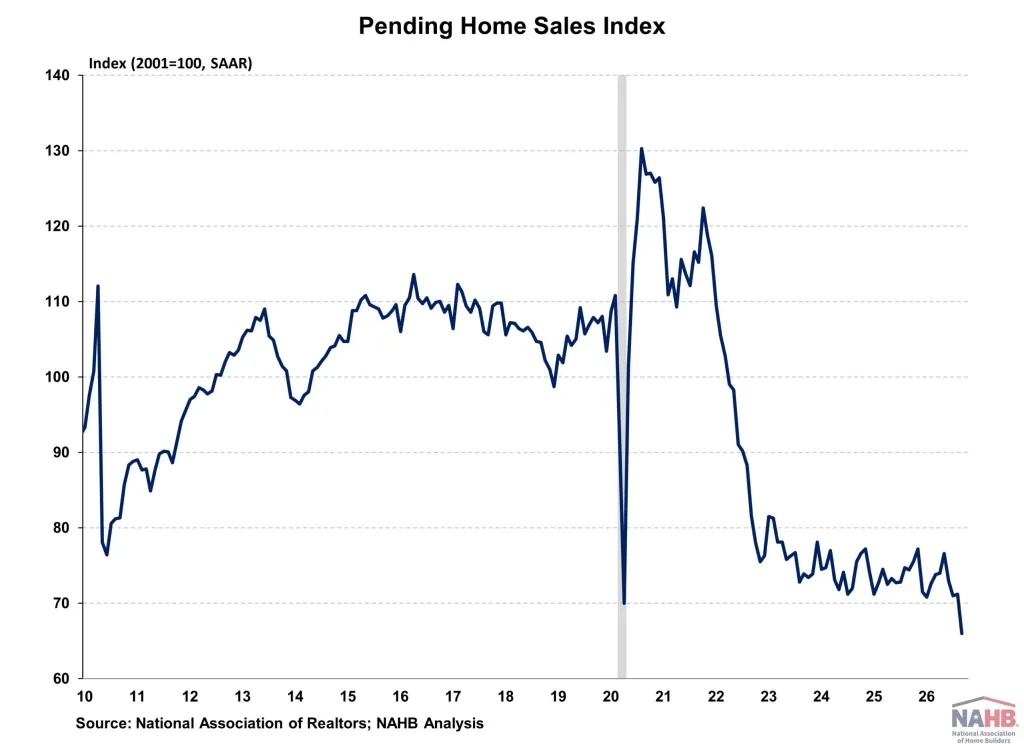
The Pending Home Sales Index (PHSI) is a forward-looking indicator that is calculated using signed contracts.
September marked the lowest level of the PHSI since NAR began monitoring it in 2001, with a decrease from 71.2 to 66.0.
The National Association of Realtors’ data indicates that pending sales were 11.3% lower than they were a year ago on a year-over-year basis.
[Read more about this topic on eyeonhousing.org]