
Buyers were burdened by record-high home prices and elevated mortgage rates, resulting in a third consecutive month of declines in existing home sales.
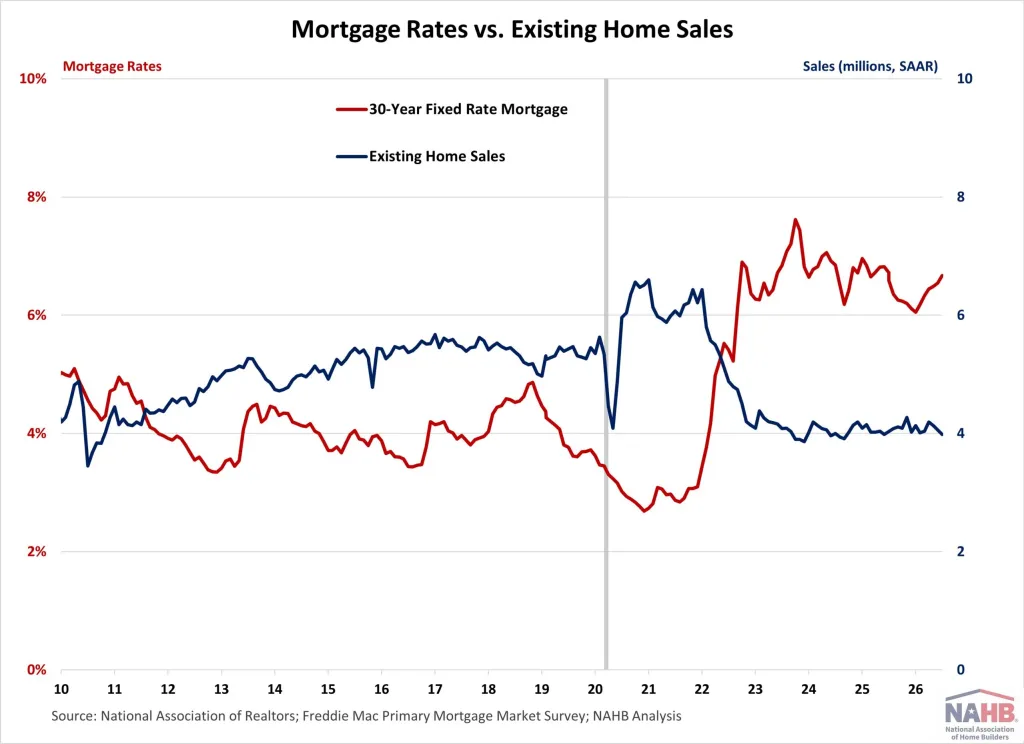
After the July ceasefire concluded, mortgage rates resumed their upward trajectory.
The 6.71% rate, which was the highest since July 2025, was reached last week as a result of inflation concerns, a bond market sell-off, and geopolitical uncertainty.
The for-sale inventory has reached its highest level in over a decade, and homes are lingering on the market for longer as buyers wait for rate relief.
Although home price growth has slowed, the overall trend remains positive, which has resulted in affordability being beyond the reach of many potential buyers.
The National Association of Realtors (NAR) reported that the total number of existing home sales, which encompasses single-family homes, townhomes, condominiums, and co-ops, decreased by 2.0% to a seasonally adjusted annual rate of 3.98 million in August.
This was the lowest level of sales since July 2025 and the second time since October 2024 that they fell below 4.0 million.
Sales decreased by 1.2% from the previous year on a year-over-year basis.
In August, the inventory of existing homes reached 1.62 million units, representing a 3.2% increase from July and a 5.9% increase from the previous year.
The unsold inventory for August is currently at 4.9 months’ supply, which is an increase from 4.6 months last month and a year ago, at the current sales rate.
This was the most abundant month’s supply since November 2015.
A balanced market is generally defined as having an inventory of 4.5 to 6 months’ supply.
The median number of days that homes were on the market in August was 31, which is an increase from the 29 days in the previous month but remains consistent with August 2025.
In August, the proportion of individuals who were purchasing for the first time was 30%.
Increased from 29% in July and 28% a year ago, the percentage increased.
The all-cash sales share in August was 27% of transactions, which is an increase from 26% last month but a decrease from 28% in August 2025.
Changes in interest rates have a lesser impact on purchasers who pay in cash.
The median sales price of all existing properties in August was $429,100, which represents a 1.6% increase from the previous year. This month represents the 38th consecutive month of year-over-year growth.
In August, the median condominium/co-op price increased by 1.5% from the previous year to $371,600.
In the majority of markets, the recent increase in home inventory will result in a downward pressure on resale home prices in 2026.
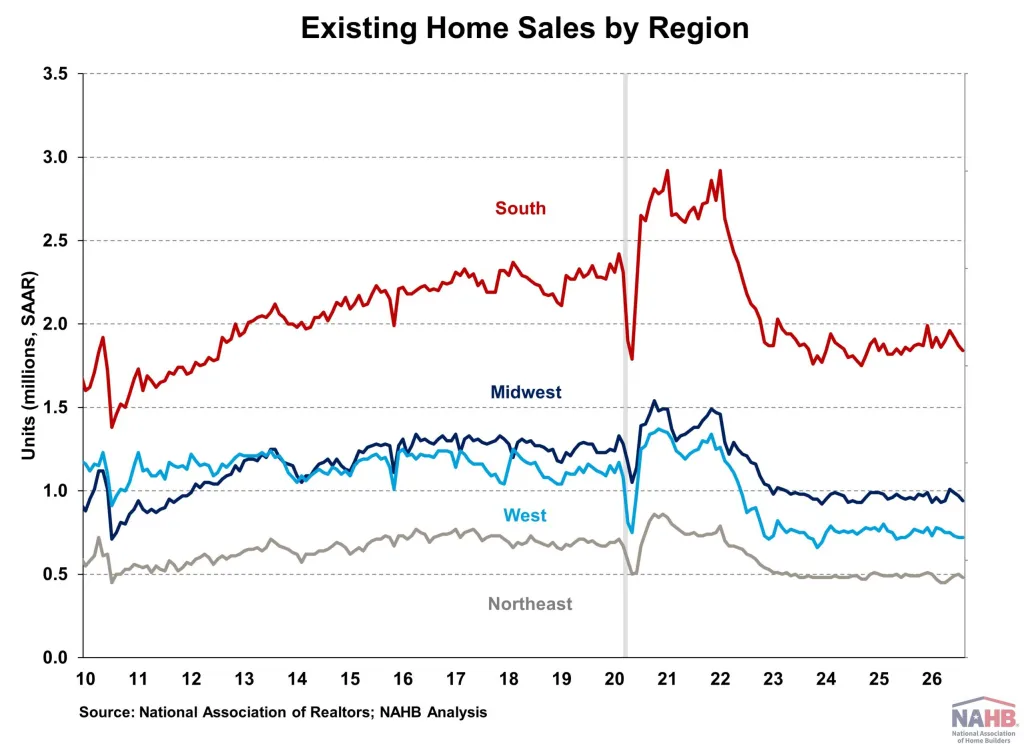
The four main regions experienced a significant decline in existing home sales during August.
Sales declined in the Northeast (-4.0%), Midwest (-3.1%), and South (-1.6%), while they remained unchanged in the West.
Sales in the West (-2.7%), Midwest (-2.1%), and Northeast (-2.0%) declined year over year, while sales in the South remained constant.
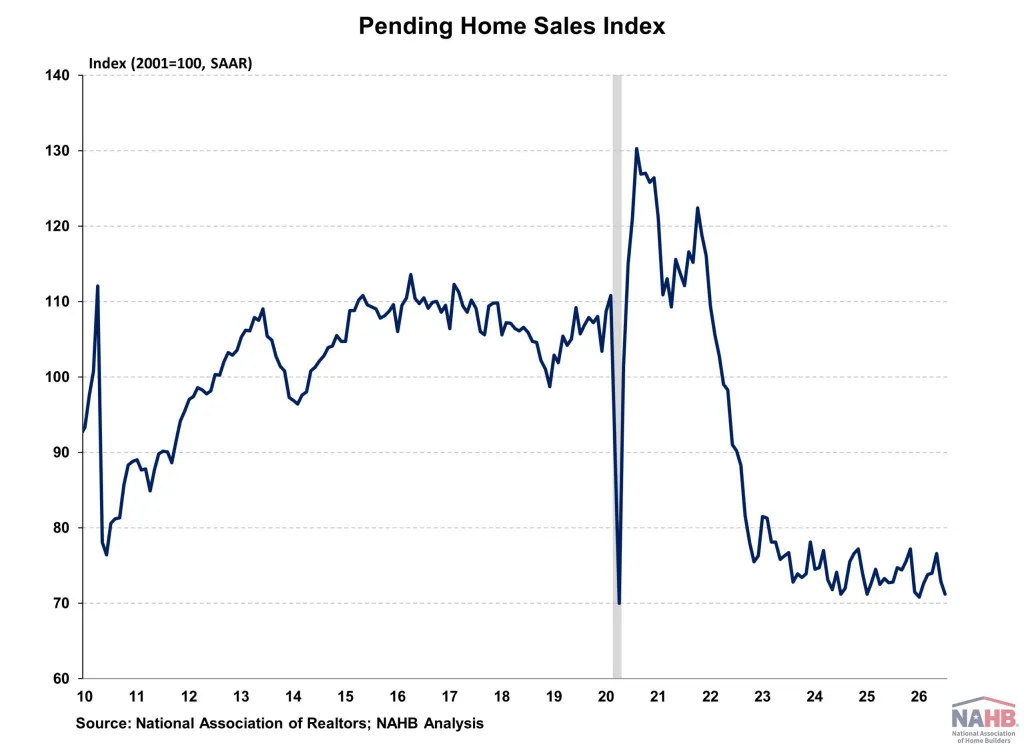
The Pending Home Sales Index (PHSI) is a forward-looking indicator that is calculated using signed contracts.
July’s PHSI dropped from 72.9 to 71.2, marking the lowest reading since January 2026.
The National Association of Realtors’ data indicates that pending transactions were 2.2% lower than they were a year ago on a year-over-year basis.
[Read more about this topic on eyeonhousing.org]